
SEBI notified the LODR Fifth Amendment Regulations, 2025, on November 18, 2025, through Gazette No. SEBI/LAD-NRO/GN/2025/273. The old flat threshold of ₹1,000 crore or 10% of turnover no longer applies. In its place, SEBI introduced a tiered, scale-based structure where the materiality limit is calculated from each company’s annual consolidated turnover, with an absolute cap of ₹5,000 crore. Every RPT needs an audit committee sign-off before execution. When a deal crosses the materiality threshold, it also requires a shareholder vote, and the related party cannot vote on their own deal. CEO and CFO certification, along with standardised disclosure formats, became mandatory from September 1, 2025. Retail investors can check quarterly and half-yearly RPT filings on BSE and NSE to track who is transacting with the company and at what value.
Picture this: a promoter’s private firm quietly wins a ₹600 crore contract from the listed company he runs. No public announcement, no shareholder vote, no pricing justification in the public domain. By the time a retail investor spots it in the annual report, the money has already moved.
This is not a hypothetical. It is the kind of situation that SEBI’s regulations on Related Party Transactions were written to prevent. And in 2025, SEBI rewrote those rules more thoroughly than it had in nearly a decade.
The changes include a company-size-based threshold model, a requirement that the CEO and CFO personally stand behind each material deal, standardised documents that investors can actually compare across companies, and the ability to read an independent valuation before a shareholder vote takes place. This guide takes you through each of these changes, explains how the numbers work, and shows you how to apply this knowledge when you look at a company before investing.
A Related Party Transaction (RPT) is any exchange of money, goods, services, or obligations between a listed company (or one of its subsidiaries) and a party that shares a close connection with that company.
Under SEBI’s Listing Obligations and Disclosure Requirements (LODR) Regulations, a related party includes:
Here is a scenario that the older rules could not catch. A promoter arranges a deal with his school friend’s company, which has no formal link to the promoter at all. The pricing is generous. The benefit flows quietly back to the promoter through a side arrangement.
Under the April 2023 amendment, SEBI closed this door. If the purpose or effect of a transaction, even with a fully unrelated third party, is to benefit a related party, it counts as an RPT. The formal connection is no longer the only test.
Arm’s length means the deal is priced as though both sides had no relationship whatsoever. Think of it as the price two strangers would negotiate in an open market. If a promoter’s consultancy firm charges three times the going market rate for advisory services to the listed company, that is not arm’s length, regardless of what the invoice says.
A transaction is material when the total value of all deals between the company and one specific related party in a financial year crosses the threshold that requires shareholder approval, not just the audit committee’s review. Once the transaction is material, the related party cannot vote on the resolution approving it.
The old framework under Regulation 23 had one fixed rule for every listed company in India. If the total RPT value with a single related party exceeded ₹1,000 crore or 10% of annual consolidated turnover, whichever was lower, the deal was material and needed shareholders to vote.
On paper, this sounds reasonable. In practice, it created problems at both ends of the spectrum.
For a conglomerate with ₹80,000 crore in turnover, ₹1,000 crore is a relatively small transaction. Routine group-level commercial arrangements, shared services, logistics, and brand licensing triggered full shareholder approval votes that added cost and time without protecting anyone from a real governance risk.
For a company with ₹500 crore in turnover, the ₹1,000 crore cap was so high that promoters could transfer substantial value to their private entities and bypass shareholders entirely. A deal worth ₹400 crore at a ₹500 crore company is enormous by any standard. Under the old rules, it needed only an audit committee sign-off.
The third gap was disclosure quality. There was no standard format. Companies could hand the audit committee whatever information they chose. Some provided detailed pricing justifications. Others gave bare-minimum descriptions. Shareholders voted without access to any independent valuation.
SEBI notified the LODR Fifth Amendment Regulations, 2025, on November 18, 2025, through Gazette Notification No. SEBI/LAD-NRO/GN/2025/273. The new framework addresses all three of these problems.
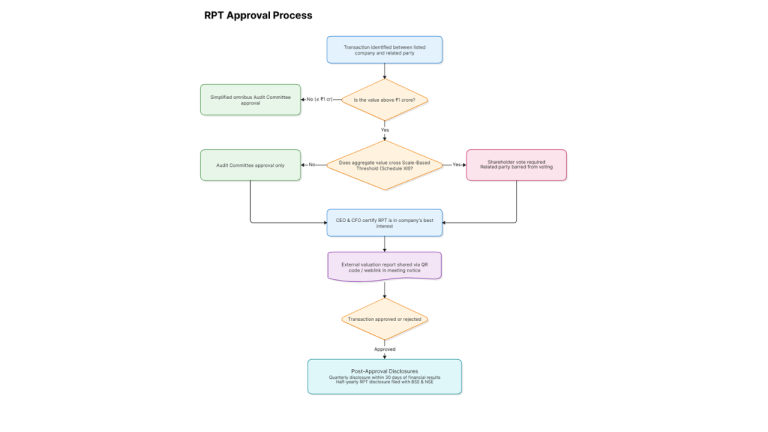
Before any RPT is executed, regardless of its size or value, it must receive prior approval from the Audit Committee. This committee is made up of independent directors whose job is to look at financial transactions from the perspective of shareholders, not management.
For RPTs below ₹1 crore, the audit committee can issue omnibus approval, a standing approval that covers an entire category of similar future transactions, so each one does not need a fresh sign-off.
When a deal is material, it requires shareholders to vote — and the related party on the other side of that deal is not allowed to cast a ballot. Materiality is now calculated using the Scale-Based Threshold (SBT) under Schedule XII of the LODR Fifth Amendment Regulations, 2025:
Annual Consolidated Turnover | Materiality Threshold |
Up to ₹1,000 crore | 10% of annual consolidated turnover |
Above ₹1,000 crore up to ₹5,000 crore | ₹100 crore plus 5% of turnover above ₹1,000 crore |
Above ₹5,000 crore | ₹300 crore plus 2% of turnover above ₹5,000 crore, subject to a maximum cap of ₹5,000 crore |
Source: Schedule XII, SEBI LODR Fifth Amendment Regulations, 2025, Gazette No. SEBI/LAD-NRO/GN/2025/273, November 18, 2025
The ₹5,000 crore ceiling applies to every listed company, no matter how large. Once the aggregate value of transactions with a single related party in a financial year crosses ₹5,000 crore, shareholders must vote. No exceptions.
One thing many investors overlook: the threshold counts the total of all transactions with one related party across the entire financial year, not each deal individually. A company cannot divide a ₹700 crore arrangement into seven monthly payments of ₹100 crore to stay under its threshold. SEBI looks at the aggregate.
There is also a separate rule for royalties and brand usage fees. If a company pays a related party royalties or brand fees that exceed 5% of annual consolidated turnover, that transaction is automatically material, regardless of where it sits relative to the Schedule XII threshold. This rule has not changed in the 2025 amendments and continues to apply independently.
Company A: Annual consolidated turnover of ₹15,000 crore
This company falls in the above ₹5,000 crore bracket.
Threshold = ₹300 crore plus 2% of (₹15,000 crore minus ₹5,000 crore)
= ₹300 crore plus 2% of ₹10,000 crore
= ₹300 crore plus ₹200 crore
Materiality threshold = ₹500 crore
Any aggregate transaction with a single related party exceeding ₹500 crore in a year needs shareholder approval.
Company B: Annual consolidated turnover of ₹3,000 crore
This company falls in the above ₹1,000 crore to ₹5,000 crore bracket.
Threshold = ₹100 crore plus 5% of (₹3,000 crore minus ₹1,000 crore)
= ₹100 crore plus 5% of ₹2,000 crore
= ₹100 crore plus ₹100 crore
Materiality threshold = ₹200 crore
If you want to learn how to put these numbers in context when reading a company’s financials, the fundamental analysis guide for Indian stocks on Alice Blue covers how to read company statements from the beginning.
SEBI’s revised Industry Standards came into force on September 1, 2025, as notified through Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/93 dated June 26, 2025. These standards were not written solely by SEBI. They were developed by the Industry Standards Forum (ISF), a body jointly comprising ASSOCHAM, FICCI, and CII, working under the supervision of SEBI and the stock exchanges.
On October 13, 2025, Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/135 introduced a simplified disclosure format called Annexure-13A and drew a clearer line between transactions that need full disclosures and those that qualify for a shorter format. That circular came into effect immediately on the date of issuance.
Table A: When Is Approval Required?
Transaction Value | Approval Required |
Below ₹1 crore | Audit Committee simplified omnibus approval |
₹1 crore up to the scale-based materiality threshold | Audit Committee approval |
Above the materiality threshold | Audit Committee approval plus shareholder vote |
Above ₹5,000 crore aggregate with one party in a year | Audit Committee approval plus shareholder vote — absolute cap regardless of company size |
Table B: What Must Companies Disclose?
Transaction Value | Disclosure Required |
Below ₹1 crore | Exempt from Industry Standards |
Does not exceed 1% of annual consolidated turnover or ₹10 crore, whichever is lower | Simplified Annexure-13A format |
Exceeds ₹10 crore or crosses the materiality threshold | Full disclosure under Industry Standards covering Part A, B, and C, including pricing justification, arm’s length assessment, and KMP certification |
Source: SEBI Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/93, June 26, 2025 and SEBI Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/135, October 13, 2025
The full disclosure format introduced through the February 14, 2025 circular (No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/18) has seven categories of information. These cover both balance sheet items like loans, guarantees, and investments, as well as profit and loss items like purchases, sales, and royalties. This seven-category structure is what ensures consistent, comparable disclosures across companies for the first time.
For material RPTs, companies must file transaction details with BSE and NSE every quarter, within 30 days of publishing their financial results for that quarter. Every listed company also files a half-yearly RPT disclosure covering all transactions, material and non-material, in a prescribed format.
Both sets of filings sit in the public domain. You do not need a subscription, a terminal, or industry contacts to access them. The Alice Blue guide on how to cross-check stock market data on BSE and NSE shows you exactly how to navigate the exchange filing sections on both websites.
Before the audit committee reviews a material RPT, the CEO or Whole-Time Director and the CFO must sign a certificate confirming that the proposed transaction is in the best interest of the listed entity. This has been mandatory from September 1, 2025, per Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/93. The earlier requirement for promoter certification was removed at the same time.
Before this rule, the person most likely to benefit from an RPT was often the one certifying its fairness. Now the certification sits with named executives who are accountable to the board and the regulator, not the promoter.
For material RPTs that go to a shareholder vote, companies must provide the external valuation report or expert opinion through a weblink or QR code embedded in the meeting notice. Shareholders can scan the QR code before casting their vote and access an independent assessment of whether the pricing is fair.
Before these rules, shareholders often received a brief description of the transaction, a statement that it was at arm’s length, and little else. The access to independent valuation changes in a practical way.
Shareholders can grant omnibus approval for a category of recurring RPTs without voting on each transaction separately. Regulation 23(4) of the LODR Fifth Amendment Regulations, 2025 now formally sets the validity periods:
Suppose a listed company’s subsidiary enters into a deal with the promoter’s private firm. The listed parent company is not a party to that contract. Under the older LODR rules, this kind of arrangement could sometimes slip below the audit committee’s radar.
Under the current rules, audit committee approval is required at the listed parent level if the value of that subsidiary-level deal exceeds ₹1 crore AND crosses the lower of:
For subsidiaries that do not have a full year of audited accounts, the test uses the lower of 10% of aggregate paid-up share capital plus securities premium, or the parent’s Schedule XII threshold. This amount must be computed as of a date no more than three months before the approval date.
Source: Regulation 23(2), LODR Fifth Amendment Regulations, 2025
From April 1, 2025, the RPT rules apply to SME-listed companies with paid-up equity capital above ₹10 crore or net worth above ₹25 crore. Their materiality threshold is ₹50 crore or 10% of annual consolidated turnover, whichever is lower. For context on how SME listings work and what rules govern them, the Alice Blue guide on SEBI IPO regulations in India covers the broader framework.
A practical exemption was added through Regulation 23(5) of the LODR Fifth Amendment. Retail purchases made by directors, KMPs, and their relatives from the listed company or its subsidiaries do not count as RPTs, as long as those purchases are on the same uniform terms available to all directors and KMPs. This removes the compliance burden of logging routine personal purchases by insiders.
Company: Rathi Textiles Ltd, listed on NSE
Annual consolidated turnover: ₹15,000 crore
Related party: Rathi Logistics Pvt Ltd, a company owned by the promoter
Deal: ₹600 crore logistics services contract over two years
Under the old rules:
Threshold = lower of ₹1,000 crore or 10% of ₹15,000 crore (₹1,500 crore) = ₹1,000 crore
₹600 crore falls below ₹1,000 crore. Audit Committee approval only. No shareholder vote.
Under the 2025 rules:
Threshold = ₹300 crore plus 2% of (₹15,000 crore minus ₹5,000 crore) = ₹300 crore plus ₹200 crore = ₹500 crore
₹600 crore exceeds ₹500 crore. Shareholder vote is now required.
Notice what this example shows. The same deal that would have cleared on audit committee approval alone under the old rules now goes to shareholders under the new ones. For mid-sized companies, the 2025 rules are actually stricter, not more lenient. The narrative that SEBI weakened investor protection in 2025 does not hold up once you look at the numbers for this segment.
The ₹5,000 crore cap gives minority investors a hard floor of protection on the largest deals, regardless of how big the company is. The standardised Part A, B, and C disclosures mean every company must now put the same categories of information in front of the audit committee and shareholders, no longer selective presentations. The QR code access to independent valuation reports means you can check whether the price on a material deal is reasonable before the vote takes place. Quarterly and half-yearly filings on BSE and NSE give you a running picture of promoter-linked deal activity throughout the year, not just once the annual report arrives.
A conglomerate with ₹50,000 crore in turnover no longer faces mandatory shareholder votes on every transaction above ₹1,000 crore. Under Schedule XII, their threshold is calculated at ₹300 crore plus 2% of ₹45,000 crore, which gives a much higher limit aligned with the actual scale of their operations. The Annexure-13A simplified format also reduces the documentation load for routine low-value RPTs. Compliance effort is now concentrated where governance risk is genuinely higher.
Feature | Before November 2025 | After November 2025 |
Materiality threshold | ₹1,000 crore or 10% of turnover, lower of the two | Schedule XII tiers based on turnover, capped at ₹5,000 crore |
Threshold calculation | Per individual transaction | Aggregate with one related party across a full financial year |
Royalty and brand usage | 5% of turnover applies independently | Unchanged, still applies independently at 5% of turnover |
SME-listed companies | Not covered | Covered from April 1, 2025, for eligible companies |
Disclosure format | No standard format | Three-part framework (Parts A, B, C) from September 1, 2025 |
Simplified disclosure | Not available | Annexure-13A for transactions up to ₹10 crore or 1% of turnover |
Subsidiary RPTs | 10% of the subsidiary’s standalone turnover | Lower of the parent’s Schedule XII threshold or 10% of the subsidiary’s standalone turnover |
Certification | Promoter, CEO, and CFO | CEO and CFO only, from September 1, 2025 |
Valuation access for shareholders | Not required | External valuation via QR code or weblink in meeting notice |
Omnibus shareholder approval | Informally permitted | Formally in Regulation 23(4): 15 months at AGM, 12 months otherwise |
Quarterly exchange filing | Required | Required within 30 days of financial results |
Retail purchases by directors | Not separately addressed | Exempt if on uniform terms for all directors and KMPs |
The rules discussed in this guide exist specifically to protect people who hold a small stake and have no seat at the boardroom table. Here is a practical approach to putting them to use.
Before you buy a stock, pull the company’s quarterly and half-yearly RPT filings from BSE or NSE. Look at the aggregate values, the names of the related parties, and the nature of the transactions. A company where 30% to 40% of revenue flows through promoter-affiliated entities, year after year, is worth examining in detail.
Go to the audit committee report in the annual report. If the committee flagged any concerns about a specific RPT or if it declined to approve something, that observation tells you more than most analyst notes will.
Look at shareholder vote outcomes for material RPTs. When a substantial proportion of non-promoter shareholders vote against a deal, they are telling you they found the terms unfair. That vote is public information and available in stock exchange filings.
For any material RPT voted on after September 2025, the external valuation report is accessible through the QR code or weblink in the meeting notice. Read it. The independent assessor’s view on whether the price is fair is the most direct proxy you have for arm’s length pricing.
Watch the royalty line item in notes to accounts every year, not just once. A royalty percentage that creeps from 1% to 2% to 3.5% of turnover over five years tells a story.
If you are reviewing a company ahead of an IPO, the Alice Blue guide on IPO red flags every investor must check also covers how related-party disclosures in the DRHP signal governance quality before a company even lists.
Most retail investors never open a company’s RPT filings. The 2025 framework makes that a more costly oversight than it used to be, because the information now available is substantially better than what existed before. The Schedule XII thresholds are calibrated to company size, the disclosures are standardised across companies, independent valuations are in investors’ hands before votes happen, and specific individuals are on record about each material deal. The tools exist. Using them is what separates an investor who understands what they own from one who is simply hoping for the best.
It is any transfer of money, goods, services, or obligations between a listed company or its subsidiary and a related party, such as a promoter, director, KMP, or an entity connected to them. From April 2023, deals with third parties that are structured to benefit a related party also qualify under the benefit-of clause.
It is now a three-tier calculation under Schedule XII of the LODR Fifth Amendment Regulations, 2025. Companies with a turnover of up to ₹1,000 crore use 10% of their annual consolidated turnover. Companies with turnover between ₹1,000 crore and ₹5,000 crore use ₹100 crore plus 5% of the amount above ₹1,000 crore. Companies above ₹5,000 crore use ₹300 crore plus 2% of the amount above ₹5,000 crore, with an absolute ceiling of ₹5,000 crore.
In aggregate. All transactions with one specific related party throughout a full financial year are added together and measured against the threshold. Splitting a large deal into smaller transactions across the same financial year does not help a company avoid the materiality limit.
The revised Industry Standards became effective September 1, 2025, per Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/93 dated June 26, 2025. The threshold clarification and Annexure-13A came through Circular No. SEBI/HO/CFD/CFD-PoD-2/P/CIR/2025/135 dated October 13, 2025.
From September 1, 2025, the CEO or Whole-Time Director and the CFO must personally certify to the audit committee that the proposed RPT is in the best interest of the listed entity. The earlier promoter certification requirement was removed at the same time.
Omnibus approval is a blanket authorisation that allows shareholders to pre-approve a category of future RPTs without voting on each transaction individually. Under Regulation 23(4) of the LODR Fifth Amendment Regulations, 2025, this is valid for 15 months when passed at an AGM and for 12 months when passed at any other general meeting.
Yes. Royalty payments and brand usage fees to a related party are automatically classified as material if they exceed 5% of annual consolidated turnover, irrespective of where the company sits in the Schedule XII tiers.
Transactions between a listed holding company and its 100% wholly-owned subsidiary, where that subsidiary’s accounts are consolidated with the listed parent and placed before shareholders, are exempt under Regulation 23(5)(b). This exemption applies only when the holding company itself is a listed entity.
Attention Investors!
Stock Brokers can accept securities as margin from clients only by way of pledge in the depository system w.e.f. September 1, 2020. Update your mobile number & email Id with your stock broker/depository participant and receive OTP directly from the depository on your email id and/or mobile number to create a pledge. Pay 20% upfront margin of the transaction early to trade in the cash market segment. Investors may please refer to the Exchange’s Frequently Asked Questions (FAQs) issued vide circular reference NSE/INSP/45191 dated July 31, 2020, and NSE/INSP/45534 dated August 31, 2020, and other guidelines issued from time to time in this regard. Check your Securities /MF/ Bonds in the consolidated account statement issued by NSDL/CDSL every month.
Corporate Office: No. 153/2, 3rd Floor, M.R.B.Arcade, Bagalur Main Road, Dwaraka Nagar, Yelahanka, Bengaluru – 560 063, Karnataka.
Registered Office: Old No.56/2 ,New No.58, LIC Nagar, Vinayagar Kovil Street, Erode -8,Tamil Nadu– 638002.
Alice Blue Financial Services (P) Ltd : NSE EQ | NSE FO | NSE CDS-90112 SEBI REG : INZ000156038
Alice Blue Financial Services (P) Ltd : BSE EQ | BSE FO | BSE CD-6670 SEBI REG : INZ000156038
Alice Blue Financial Services (P) Ltd : CDSL DP ID 12085300 DP SEBI REG : IN-DP-364-2018
Alice Blue Financial Services (P) Ltd : MCX-56710 SEBI REG : INZ000156038
We hereby declare that we are doing PRO trading
Procedure to file a complaint on SEBI SCORES : Register on SEBI SCORES 2.0. Mandatory details for filing complaints on SCORES: Name, PAN, Address, Mobile Number, E-mail ID. Benefits: Effective Communication, Speedy redressal of the grievances
Click on the provided link to learn about the process for submitting a complaint on the ODR platform for resolving investor grievances.
Investment in securities markets are subject to market risks, read all the related documents carefully before investing. Brokerage will not exceed SEBI prescribed limit.
For queries regarding account opening or activation, email to [email protected] and for fund updates, email to [email protected]
Disclaimer : Prevent unauthorized transactions in your account. Update your mobile numbers/email IDs with your stock brokers. Receive information of your transactions directly from Exchange on your mobile/email at the end of the day. Issued in the interest of investors. All clients have to update their email id and mobile number with Member : Investor Grievance [email protected]
KYC is a one time exercise while dealing in securities markets – once KYC is done through a SEBI registered intermediary (broker, DP, Mutual Fund etc.), you need not undergo the same process again when you approach another intermediary.
No need to issue cheques by investors while subscribing to an IPO. Just write the bank account number and sign in the application form to authorise your bank to make payment in case of allotment. No worries for refund as the money remains in the investor’s account.
Investors are requested to note that Alice Blue Financial Services Private Limited is permitted to receive money from investor through designated bank accounts only named as Up streaming Client Nodal Bank Account (USCNBA). Alice Blue Financial Services Private Limited is also required to disclose these USCNB accounts to Stock Exchange. Hence, you are requested to use following USCNB accounts only for the purpose of dealings in your trading account with us. The details of these USCNB accounts are also displayed by Stock Exchanges on their website under “Know/ Locate your Stock Broker. Bank Details (Valid UPI FAQ).


